
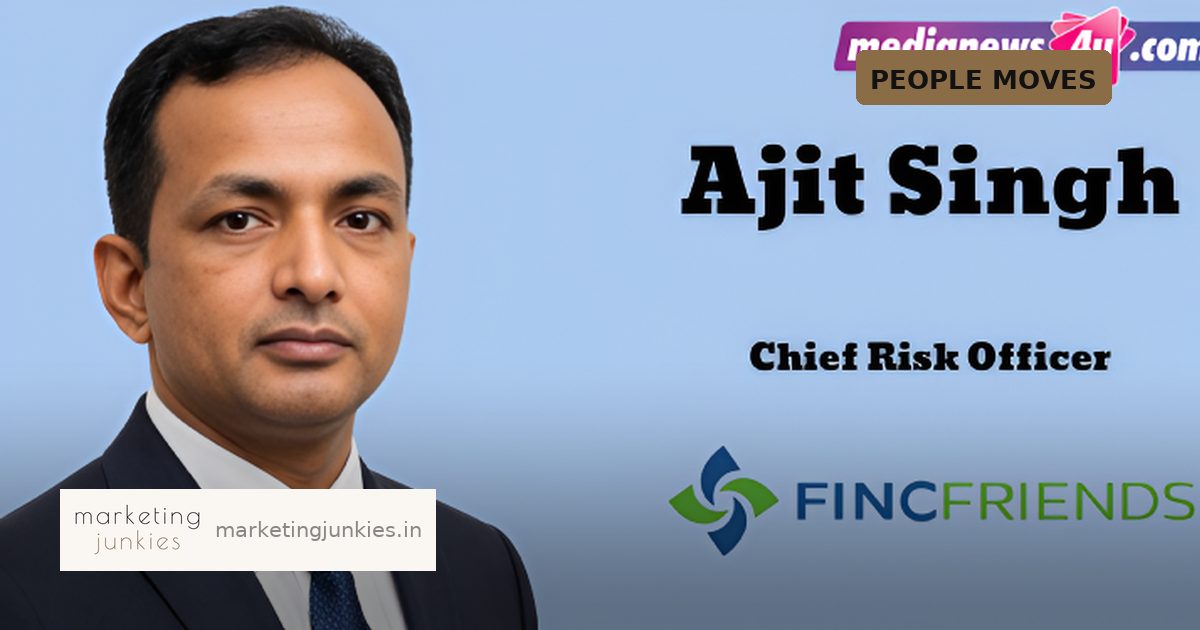
FincFriends, the non-banking financial company that operates the RupeeRedee lending brand, has appointed Ajit Singh as its Chief Risk Officer. The hire comes as the company pushes to scale its lending book and tighten its risk governance framework in India’s fast-growing digital lending market.
Singh arrives with 22 years of experience across consumer lending and fintech, having held senior positions at True Balance, Stashfin and Home Credit India. His work at those companies spanned credit underwriting, fraud controls, portfolio analytics and governance — the full stack of a modern lender’s risk function. He holds a Master’s degree in Mathematics and Computer Applications and is a qualified Associate of LOMA (United States).
What the role covers
At FincFriends, Singh will own credit risk, operational risk and fraud risk, working alongside business and technology teams to refresh controls as the portfolio grows. The company has also flagged his experience with AI-driven risk tools and advanced analytics as an input into how it makes credit decisions and manages its portfolio.
CEO Artem Andreev said Singh brings “exactly the kind of experience we need at this point in our growth,” adding that risk management at the company is not treated purely as a compliance box-tick but as the function that allows the business to grow with confidence.
Singh, for his part, said his focus will be on sharper risk frameworks, data-driven credit decisions and controls that keep pace with growth. “When risk works well, it does not slow a company down,” he said, framing the function as an enabler of speed rather than a brake.
Why a risk hire matters to marketers
On the face of it, a Chief Risk Officer appointment sits far from the marketing floor. In lending, it rarely does. Three reasons this hire is worth noting for anyone working on a financial services brand:
- Approval rates shape campaign economics. Performance marketing in lending is judged on cost per disbursal, not cost per lead. A tighter, better-calibrated risk model changes how many applicants convert — and therefore what a marketing team can afford to pay per click.
- Fraud controls protect acquisition spend. Fraud risk sits inside Singh’s remit, and fraudulent applications quietly inflate acquisition budgets while degrading the data models that media buyers optimise against.
- Trust is the category’s brand promise. In digital lending, where regulatory scrutiny and consumer wariness are both high, governance credentials are increasingly part of the brand story that gets told to customers, partners and investors.
The bigger pattern in fintech leadership
FincFriends has positioned the appointment as part of a wider effort to build out its leadership bench as it expands in India. That is a familiar arc for digital lenders that have crossed from early growth into scale: after the initial land-grab, the hires shift from growth and distribution to risk, compliance and analytics leadership.
For marketing and communications teams inside such companies, the shift has practical implications. Messaging tends to move away from pure speed-of-disbursal claims towards responsible lending, transparency on charges and data protection. Category leaders have already leaned in this direction, and the regulatory environment around digital lending in India has made it less of a choice.
What to take away
If you work on a fintech or NBFC brand, the useful exercise here is a simple one: map how closely your marketing funnel is wired to your risk function. Are media buyers seeing approval and default data, or only lead volume? Is fraud flagged back into channel-level reporting? Do brand claims reflect the actual underwriting reality customers experience after they tap “apply”?
Appointments like Singh’s are a reminder that in lending, growth marketing and risk management are two halves of the same P&L. The teams that treat them as one system tend to spend better — and make fewer promises they cannot keep.
Source: MediaNews4U