
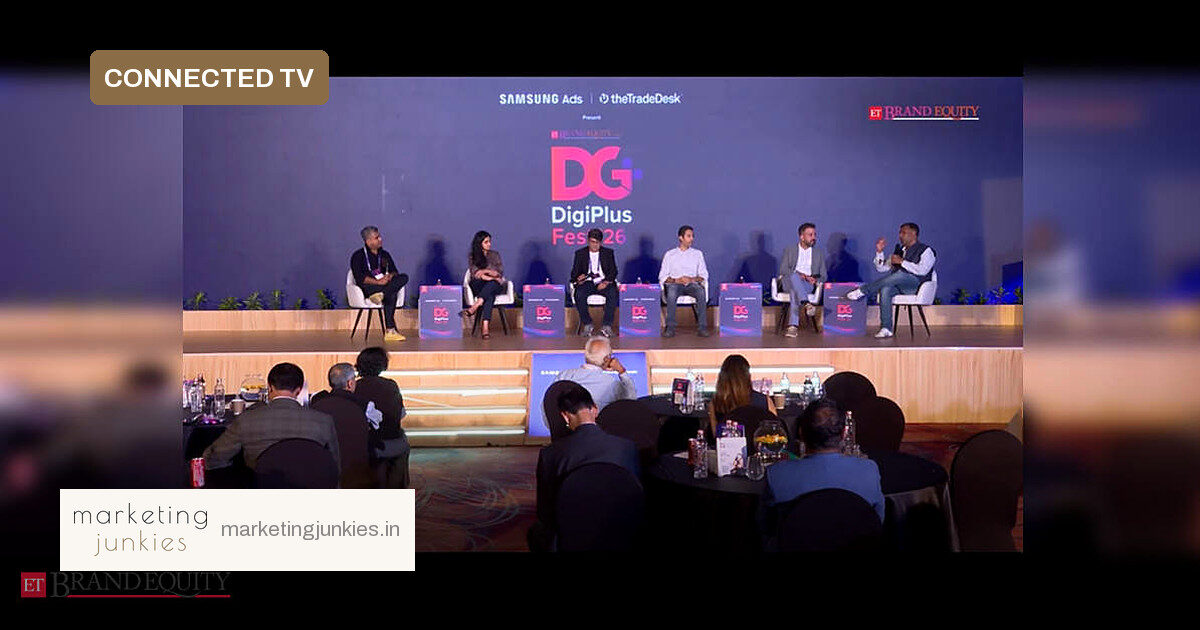
Connected TV arrived in India on a wave of ‘fear of missing out,’ but at ET DigiPlus Fest 2026 it was treated as a core planning question rather than a novelty. A panel titled ‘The Total Video Playbook: CTV as the Engine of Audience Insights and Incrementality’ brought together marketers from Eveready Industries India, DS Group, Cheil SWA, Axis Max Life and The Trade Desk to assess where CTV adds value and where it still falls short.
From FOMO to a serious media layer
Kumar Awanish, group COO at Cheil SWA, said early CTV adoption was driven by marketers’ ‘fear of missing out’ and a need to experiment before the medium’s role was clear. That has changed: the panel agreed CTV now offers sharper targeting than linear television, largely because it combines TV’s large-screen storytelling with digital precision.
Insiyah Kasim Chawala of Eveready Industries India pointed to a growing number of CTV-exclusive households, which makes the medium hard to ignore for brands trying to reach audiences linear TV misses. She said leaner budgets and niche categories are often better suited to CTV when brands combine internal first-party data with pin-code-level targeting.
Abhishek Chaudhry of DS Group put CTV on par with linear and any other medium, while Rahul Singh of The Trade Desk emphasised the large-screen environment’s ability to win ‘hearts and minds’ alongside digital measurability.
The incremental reach problem
The panel’s core warning was that CTV does not automatically add new audiences. For mass-market brands such as Catch Spices, CTV viewers may overlap heavily with those already reached through linear television, leaving little additional audience. That makes budget allocation across video platforms a genuine strategy question rather than a default shift.
Sahil Rawal of Axis Max Life said CTV can work at the top, middle and bottom of the funnel, especially for categories like life insurance where intent is hard to spot and acquisition costs are high. Metrics such as brand-search lift can help show the incremental effect, he said, but brands often need to layer independent brand-lift studies, tracking and consumer research over platform data.
Second screens and the measurement gap
A recurring theme was second-screen behaviour. Singh noted that viewers often watch TV while using a smartphone, creating a bridge from big-screen exposure to immediate phone action. The challenge is proving that an ad on CTV led to a search or purchase days later on another device.
Awanish described the complexity: a viewer sees a CTV ad and buys days later on a phone or tablet, and connecting those signals can be expensive and difficult to scale. Chaudhry added that CTV looks measurable on its own, but incrementality gets murky when it is layered with linear television. He warned that multiple layers in the CTV supply chain—DSPs, supply partners, broadcasters and OEMs—have produced too many measurement currencies, making boardroom-level investment harder without transparency and unified metrics.
What this means for media planners
The panel offered a practical sequence for marketers evaluating CTV:
- Start with first-party data. Understand viewing and purchase patterns before choosing placements, then move backwards to creative adaptations.
- Test before scaling. Run pilots in specific audiences or markets and measure awareness, trust and brand-search lift.
- Expect category differences. Niche and emotionally driven brands may see clearer incremental value than mass-market brands already heavy on linear.
- Demand unified measurement. Without transparency, CTV budgets will hit a ceiling under boardroom scrutiny.
Kasim Chawala added a long-term caution: building a brand still involves intangibles and metrics that play out over years and decades, so CTV should grow inside a wider 360-degree media ecosystem rather than replace it.
Source: ETBrandEquity.com